Front-End Rate Repricing
Front-End Curve Repricing Deepens on Renewed Tightening Risks
14 October 2026
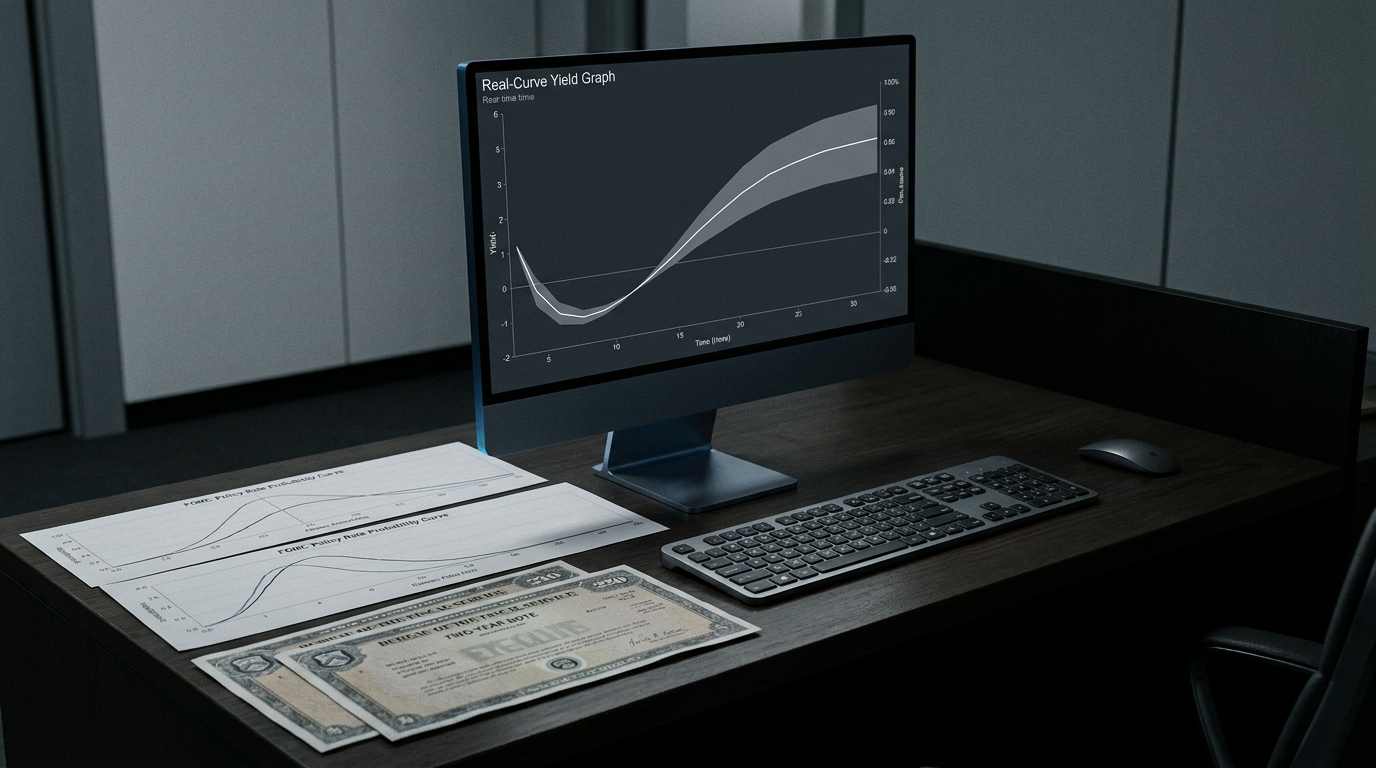
Trading across global rates markets yesterday reflected a fundamental reassessment of the path for United States monetary policy. Over the course of Tuesday's session, front-end benchmark yields reached multi-month highs as swap markets sharply repriced the distribution of terminal policy rate outcomes. Fixed-income desks, which had until recently positioned for an orderly succession of policy cuts into 2027, were compelled to absorb evidence that persistent underlying inflation components may not merely delay accommodation, but potentially necessitate an outright resumption of rate hikes.
The catalyst for this repricing stems from an accumulation of inflationary resilience across non-housing services, energy-adjacent logistics, and firm baseline wage settlements. These pressures were thrown into sharp relief by the latest macroeconomic releases and the government cost-of-living adjustments finalized this week. Rather than confirming an immaculate glide path toward the central bank's two percent mandate, the persistence of price gains across core consumer baskets indicates that real domestic absorption remains robust enough to transmit secondary price shocks through supply chains. As short-term breakevens widened, the implied probability of an incremental twenty-five basis point hike within the next two Federal Open Market Committee meetings crossed significant institutional thresholds.
For institutional capital allocators, the resurgence of policy rate asymmetry represents a structural challenge to duration posture and liability-driven frameworks. During previous tightening cycles, the inversion of the two-year to ten-year yield curve signaled that peak policy rates would generate sufficient economic decelerations to induce prompt monetary easing. However, the current configuration presents a stubborn flatness where front-end yields remain elevated above four-and-a-half percent while long-dated paper grapples with sustained fiscal debt issuance. This dynamic narrows the hedging efficiency of sovereign duration, as portfolios exposed to both policy uncertainty at the short end and term-premium expansion at the long end face simultaneous mark-to-market drawdowns.
The real economy transmission channel is already registering the impact of this hawkish repricing, most visibly across asset-backed credit and residential finance. Secondary mortgage rates, which had begun to stabilize in late summer, pushed firmly back toward the seven-and-a-quarter percent threshold during yesterday's trade. This renewed surge compounds the existing lock-in effect, preserving historically tight resale inventory and keeping shelter service metrics sticky within the aggregate inflation calculation. The resultant feedback loop leaves the Federal Reserve in an acute strategic dilemma: tightening monetary policy further risks compounding balance-sheet strains on regional banks and commercial real estate refinancing, yet inaction risks un-anchoring inflation expectations that are increasingly visible in medium-term survey data.
From the vantage point of Zurich, the cross-border implications of renewed dollar policy divergence are substantial. European and Swiss monetary authorities face divergent domestic fundamentals, characterized by more subdued industrial activity and benign headline consumer prints. A persistent wedge between the Federal Reserve's policy trajectory and that of the European Central Bank or the Swiss National Bank inevitably generates sustained upward pressure on the trade-weighted dollar. For multi-currency balance sheets, the resulting widening of cross-currency basis spreads increases the friction of hedging dollar-denominated fixed-income exposures back into domestic currencies, altering the net return calculus for non-US institutional investors.
As the Federal Reserve approaches its forthcoming policy deliberation, markets must navigate an environment where tail risks have transitioned from disinflationary stagnation back to inflation entrenchment. Forward guidance is likely to emphasize maximum optionality, eschewing definitive cycle-end declarations in favor of granular data dependency. Institutional participants must consequently adjust to elevated volatility across the short end of the curve, where the pricing of monetary policy risk can no longer be viewed as an asymmetric, one-way exercise in duration recovery.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.