Sovereign Duration Dynamics
Sovereign Duration Supply Challenges Long-End Debt Dynamics
7 October 2026
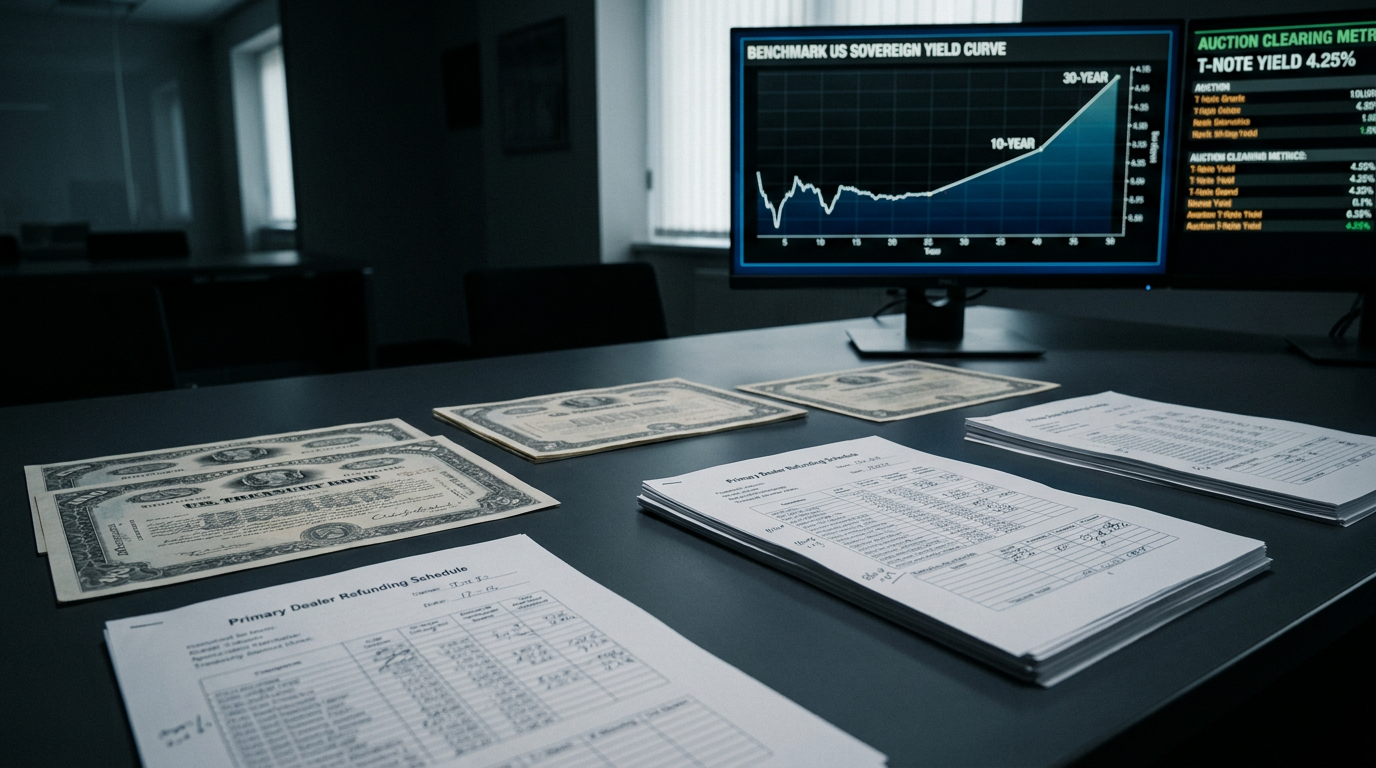
The latest release of Federal Open Market Committee minutes underscored an institutional reluctance among monetary policymakers to initiate a renewed cycle of rate tightening. However, global fixed-income markets are increasingly recognizing that the decisive determinant of long-end borrowing costs no longer resides purely within monetary deliberations. Instead, the persistent trajectory of sovereign debt issuance, paired with elevated debt-service burdens in Washington and major Western capitals, has redirected focus toward the structural absorption capacity of institutional balance sheets.
Over the past twenty-four months, sovereign debt managers utilized an elevated share of Treasury bill issuance to satisfy heightened funding requirements without precipitating acute liquidity squeezes across intermediate and long-dated tenors. While this maneuver successfully preserved liquidity conditions during the apex of monetary restriction, the mechanical limitations of running historically elevated front-end borrowing ratios are becoming apparent. Primary issuance profiles must inevitably normalize toward longer-dated benchmark coupons at a time when traditional buyers of sovereign duration are exhibiting diminished price-insensitive demand.
The global buyer base for long-dated paper has undergone profound structural reconfiguration. Foreign official institutions and central banks, historically dominant participants in long-duration auctions, have curtailed sovereign bond accumulation in favor of alternative reserve assets and domestic currency stabilization operations. Concurrently, commercial banks face persistent regulatory constraints under capital and liquidity framework revisions, limiting their capacity to intermediate primary dealer inventories or absorb duration on balance sheet without widening bid-ask spreads.
As a consequence, the clearing of multi-billion-dollar auctions in ten-year notes and thirty-year bonds relies with greater frequency on domestic mutual funds, pension schemes, and quantitative relative-value managers. These market participants operate with explicit return hurdles and strict liability-matching criteria, demanding a reconstituted term premium to warehouse duration risk against an uncertain fiscal backdrop. When auction schedules expand while central banks maintain passive balance-sheet runoff, this term premium functions as the principal adjustment mechanism, exerting persistent upward bias on back-end yields independently of central-bank target rates.
This dynamic intersects with corporate capital market behavior. While mega-cap technology corporations and top-tier industrial credits have leveraged exceptionally low-friction balance sheets to fund transformative digital infrastructure programs, secondary-tier corporate issuers confront an impending maturity schedule under materially higher refinancing hurdles. Corporate spreads over long-dated Treasuries have remained unusually tight relative to historical cycles, reflecting strong institutional demand for high-grade credit over pure sovereign duration. Yet this compression leaves corporate paper acutely vulnerable if sovereign yields remain elevated, as the absolute cost of capital begins to weigh on corporate net cash generation.
For institutional allocators, the evolving sovereign duration landscape demands a re-examination of cross-asset portfolio construction. The long-held presumption that long-dated government debt reliably serves as an uncorrelated hedge against equity drawdowns has repeatedly broken down during periods where fiscal supply dynamics overpower cyclical growth concerns. When fiscal deficits dictate curve dynamics, sovereign duration behaves less like an insurance asset and more like an active duration risk subject to liquidity concessions. Capital allocation frameworks must therefore look beyond terminal policy rates and rigorously account for the mechanical realities of sovereign debt absorption.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.