Sovereign Computing Architecture
Sovereign Data Mandates Reshape Enterprise Software Architecture
1 October 2026
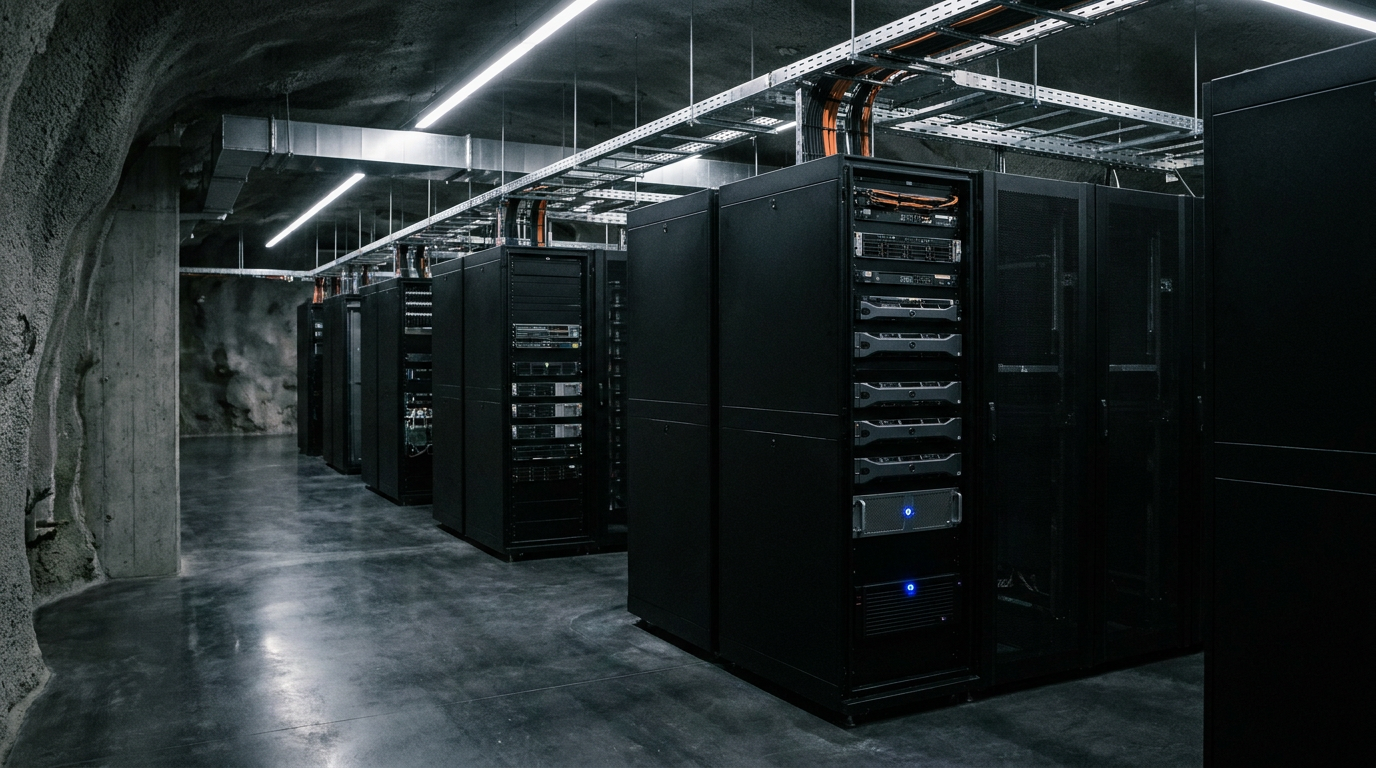
The structural premise of the modern software industry has long relied on the continuous expansion of centralized, multi-tenant public cloud infrastructure. By aggregating workloads across borderless digital environments, software providers achieved extraordinary operating leverage and industry-leading gross margins. However, trading sessions over the closing days of the third quarter highlighted an accelerating structural shift: the enterprise software architecture is fragmenting along national and jurisdictional boundaries. Driven by expanding regulatory frameworks and heightened defense readiness, demand is rotating toward sovereign computing frameworks that enforce domestic data residency, localized model execution, and cryptographic independence.
This architectural pivot was brought into sharp relief as enterprise platforms unveiled formal sovereign operational models tailored specifically to allied defense ministries and regulated civil agencies. In prior cycles, compliance was largely handled through software-defined access controls layered atop standardized hyperscale estates. That paradigm is proving insufficient under emerging regulatory scrutiny across Europe and allied territories. Legislative instruments governing digital resilience and extraterritorial jurisdiction, compounded by institutional wariness surrounding the US CLOUD Act, have made physical and operational isolation a non-negotiable prerequisite for enterprise contracts across government, utility, and banking sectors.
For institutional software vendors, adapting to sovereign requirements alters the economic baseline of product delivery. Multi-tenant efficiencies must be exchanged for dedicated sovereign enclaves, air-gapped data pipelines, and localized model fine-tuning. These installations require bespoke integration with domestic telecommunications operators and state-certified host environments. While expanding addressable market opportunities within previously inaccessible national security and public sector budgets, the sovereign approach increases capital intensity and lengthens sales cycles. Gross margins on sovereign deployments contract under the weight of localized personnel requirements, domestic infrastructure leasing, and persistent compliance audits.
Simultaneously, the competitive landscape is diverging between pure-play software aggregators and platform providers capable of managing complex sovereign compliance. Standard commercial cloud architectures that lack built-in sovereign separation risk losing market share across continental Europe, where state-backed entities are enforcing strict geographic data-sovereignty mandates. Conversely, infrastructure providers that have engineered sovereign compliance directly into their operating systems are capturing significant multi-year commitments from public-sector clients willing to pay a premium for regulatory certainty.
From the vantage point of Zurich, this fragmentation reflects a broader macroeconomic and geopolitical reality. The frictionless internationalization that powered enterprise technology valuations over the past two decades is giving way to jurisdictional segmentation. Balance-sheet discipline now requires allocating capital toward software operators that recognize this dispersion and are structurally equipped to navigate regional regulatory barriers without absorbing destructive margin erosion. Sovereign computing is no longer a defensive compliance posture; it has emerged as a primary determinant of commercial durability in enterprise software.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.