Semiconductor Capital Realignment
Foundry Asset Sharing Emerges as Fab Capex Tests Balance Sheets
28 September 2026
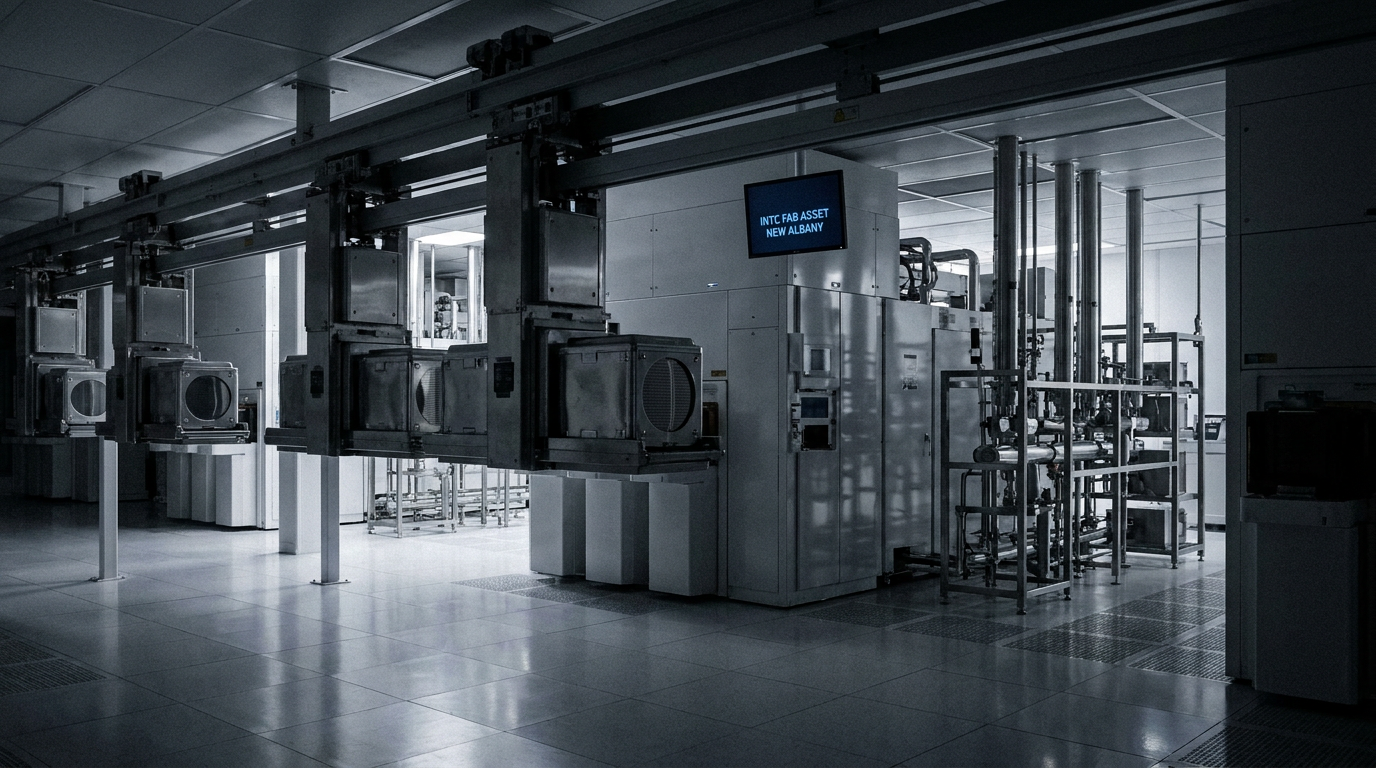
The capital requirements of leading-edge semiconductor manufacturing are forcing a pragmatic recalibration of national industrial strategies. What began as sovereign pushes toward fully integrated domestic supply chains has collided with the immense balance-sheet friction of sub-two-nanometer fabrication and high-bandwidth memory packaging. The recent disclosure that South Korea's SK Hynix is evaluating potential footprint utilization within Intel's New Albany, Ohio development site highlights an emerging structural shift: infrastructure co-location and asset-sharing between ostensible competitors seeking to de-risk massive fixed-capital commitments.
For Intel, navigating internal margin preservation alongside the balance-sheet repositioning of auxiliary assets such as Altera, the Ohio site represents both an ambitious commitment to domestic manufacturing and a considerable cash-flow burden. The project was conceived under assumptions of aggressive foundry volume ramp-ups supported by public funding allocations. However, prolonged commercial customer acquisition cycles and sustained capital costs have necessitated greater structural flexibility. Sharing site infrastructure, heavy industrial utility hookups, and specialized cleanroom shells allows the primary developer to amortize civil preparation expenditures while maintaining mandated development timelines.
On the memory side, the strategic calculus of SK Hynix reflects the compounding urgency of packaging capacity for artificial intelligence accelerators. As memory product lifecycles compress to eighteen months or fewer, proximity to advanced packaging hubs and primary wafer fabrication facilities has evolved from an operational convenience to a strategic necessity. While domestic peers like Micron Technology pursue independent greenfield facilities across multiple states, foreign manufacturers navigating overseas subsidy frameworks face formidable construction inflation and prolonged environmental permitting hurdles. Sub-leasing or co-developing pre-permitted industrial acreage within existing megasite perimeters materially accelerates time-to-market while curbing standalone execution risk.
From a macroeconomic perspective, these discussions mark the transition of semiconductor statecraft from political rhetoric into financial reality. The early phase of regional reshoring treated industrial capacity as a nationalized zero-sum contest. Yet advanced semiconductor fabrication systems, extreme ultraviolet lithography apparatus, and dedicated power grids require sustained operational utilization rates exceeding eighty-five percent to produce an acceptable return on invested capital. Unilateral, sub-scale developments risk stranding institutional capital if regional volume commitments fail to materialize at the anticipated pace.
In institutional portfolios, this emerging discipline alters the risk underwriting for merchant foundries, outsourced assembly providers, and equipment vendors. Equity valuations that previously priced in uninterrupted, duplicative capital expenditure programs must now adjust for consortium-style capacity management, joint facilities, and infrastructure syndication. Rather than witnessing a world of fragmented, isolated domestic foundries, the market is beginning to prioritize co-located fabrication clusters where sovereign compliance and capital efficiency can coexist. For institutional capital, this collaborative asset optimization provides a far more defensible financial framework for multi-year semiconductor investments.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.