Structured Credit Consolidation
CLO Consolidation Deepens as Banks Race for Scale in Private Debt
24 September 2026
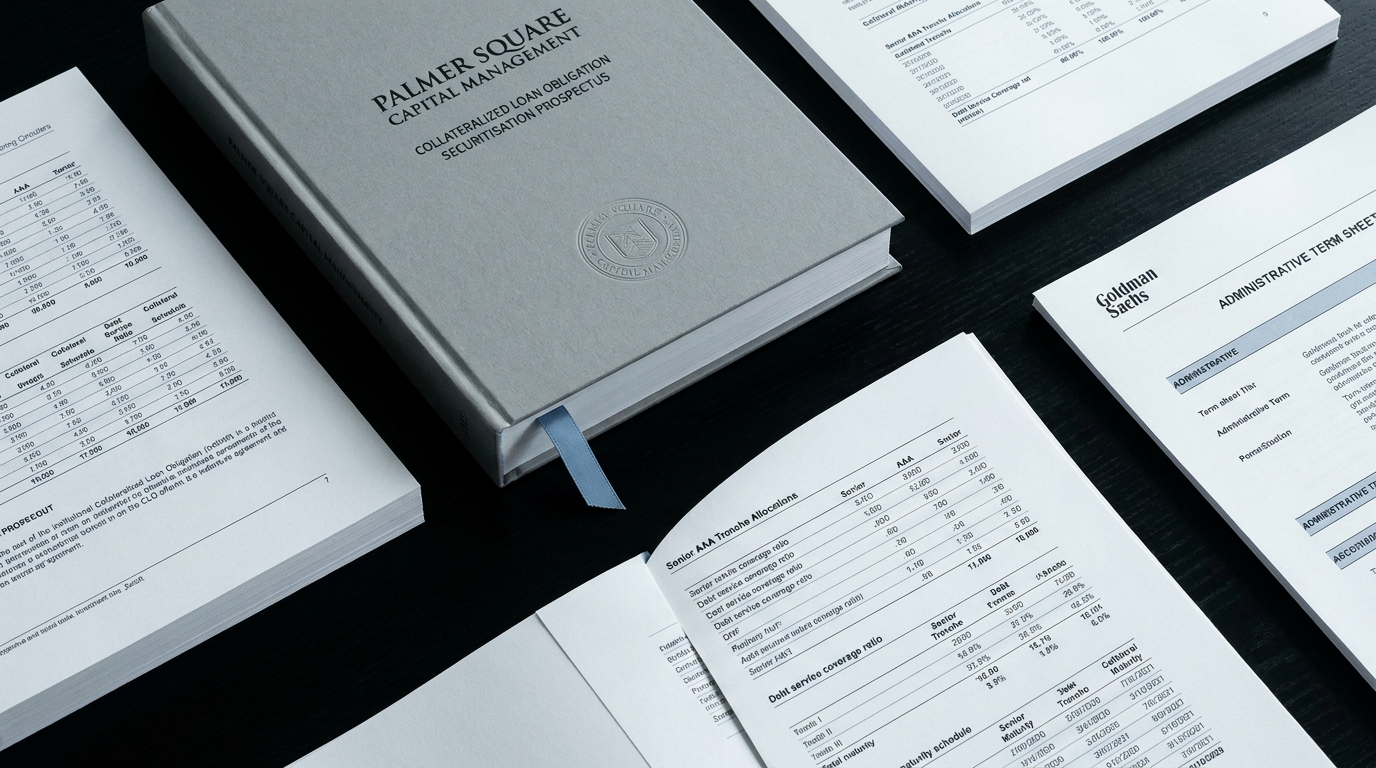
Goldman Sachs's emergence yesterday as the leading bidder for Palmer Square Capital Management, an asset manager overseeing roughly thirty-seven billion dollars heavily weighted toward collateralised loan obligations, signals a defining phase in institutional credit consolidation. The prospective transaction highlights an accelerating drive among global investment banks to secure programmatic structured credit volume. What was once considered a bespoke securitisation niche has evolved into an essential, industrialised pillar of international corporate debt syndication.
Palmer Square has distinguished itself over the past decade through disciplined issuance across both broadly syndicated and middle-market credit vehicles, standardising documentation and pioneering liquid collateralised debt structures. For an institution of Goldman Sachs's scale, acquiring such an established platform satisfies a clear operational and strategic imperative: capturing recurring fee income, expanding private debt distribution, and locking in permanent capital for corporate balance-sheet financings. As sovereign wealth funds, pension systems, and insurance groups continue to seek floating-rate yields protected by structural credit subordination, the demand for sophisticated loan repackaging remains exceptionally resilient.
This consolidation also reflects the steady convergence of the private credit and broadly syndicated loan universes. Over recent quarters, direct lending syndicates have regularly rivalled public debt syndicates for multi-billion-dollar enterprise transactions, compelling traditional balance-sheet lenders to construct hybrid deployment channels. By assimilating a programmatic vehicle issuer, an underwriting bank can route senior secured exposure into whichever structure offers optimal capital efficiency, whether through private bilateral placements, rated public tranches, or specialised middle-market vehicles.
Regulatory evolution continues to serve as an unspoken catalyst behind these corporate transactions. Under the ongoing implementation of revised Basel capital standards, carrying leveraged corporate exposure directly on banking balance sheets carries increasingly restrictive risk-weighted capital penalties. Offloading the funding of such credit to independent institutional capital—while retaining structuring, asset servicing, and ongoing administration mandates—enables major institutions to intermediate vast corporate lending volumes with minimal balance-sheet strain. The asset risk is distributed cleanly across institutional tiers, leaving the sponsoring bank with diversified, high-margin asset management revenues.
Yet the acceleration of mega-scale managers across the structured debt landscape introduces distinct systemic questions regarding market pricing and credit discipline. As secondary loan volumes concentrate among a diminishing cohort of primary underwriters, market liquidity may become increasingly dependent on continuous vehicle creation. The relentless imperative to source collateral to feed newly priced issuance can inadvertently compress risk premiums across lower-tier corporate borrowers, obscuring latent credit vulnerability during periods when underlying debt servicing costs remain structurally elevated.
For institutional allocators and family offices observing these developments from Zurich, the institutionalisation of the collateralised credit engine provides welcome operational liquidity and standardised tranching mechanisms. Nevertheless, continuous expansion does not eliminate the foundational reality of leveraged finance: underlying cash-flow resilience remains the sole determinant of terminal recoveries. In an economic climate defined by disparate sector performance and selective earnings pressure, the value of structural subordination will ultimately depend on uncompromised collateral underwriting rather than aggregate balance-sheet scale.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.