Bilateral Trade Diplomacy
Diplomatic Re-Engagement Calibrates Global Risk and Metal Flows
22 September 2026
Monday's trading session across global bourses was characterized by a distinct recalibration of institutional risk premia, as market participants positioned ahead of high-level bilateral discussions between Washington and Beijing. Equity futures climbed in steady fashion, supported by an easing in front-month crude contracts, as capital allocators factored in the possibility of reduced tariff escalation and stabilized diplomatic channels. However, beneath the buoyant headline performance of broad equity indices, underlying cross-asset behavior revealed an institutional cohort maintaining defensive hedges rather than embracing unhedged beta.
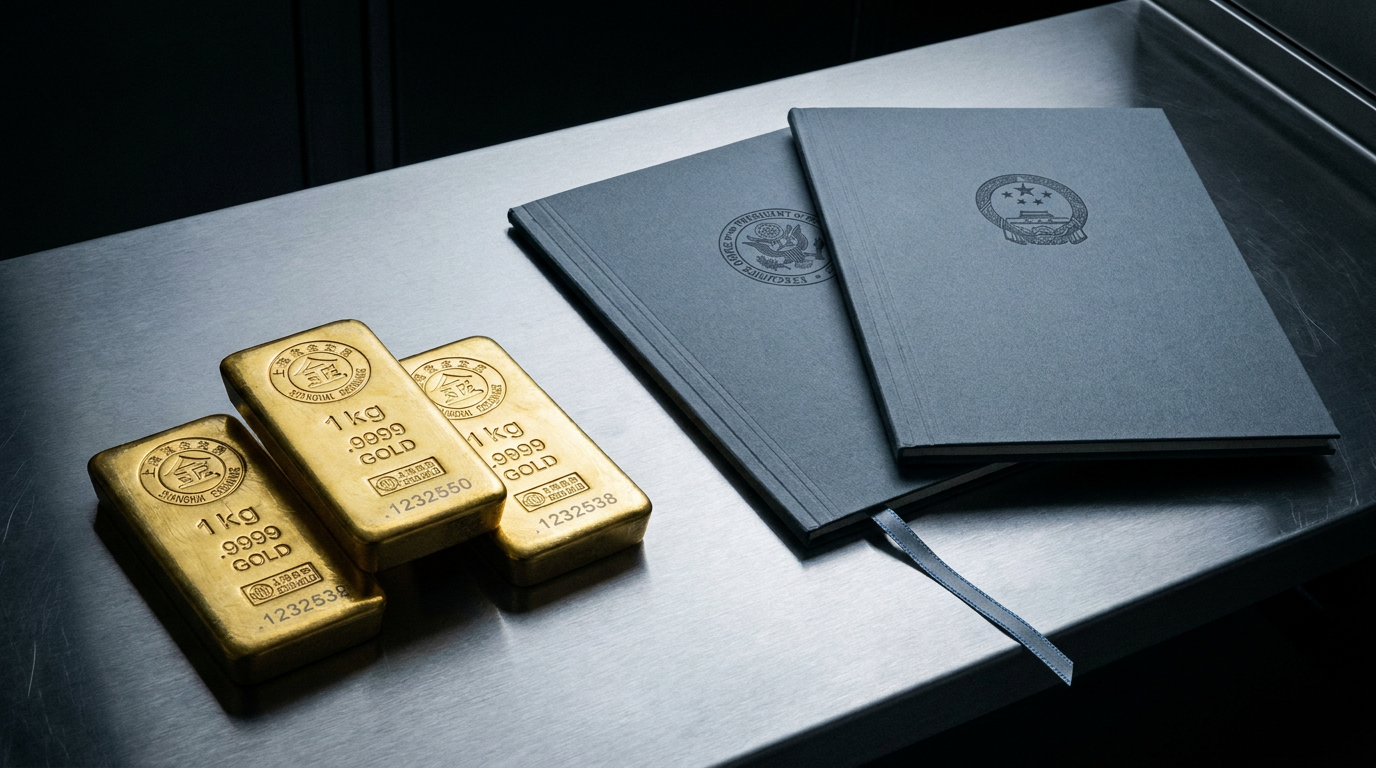
The most striking divergence unfolded across commodity complexes. While benchmark hydrocarbons yielded ground on expectations of diplomatic detente, physical precious metals exhibited profound strength. Chinese customs and trade data confirmed record-setting monthly gold import volumes, an institutional accumulation trend that provided an unyielding floor for spot bullion. Concurrently, silver advanced sharply toward multi-year peaks. The coexistence of advancing risk assets with unprecedented sovereign and institutional accumulation of physical monetary metals underscores that large-scale allocators view bilateral summitry as a tactical decompression event rather than a permanent resolution to multipolar fragmentation.
In industrial and sovereign procurement spheres, capital dispersion remains acute. Heavy industrial constituents and defense conglomerates demonstrated pronounced divergence, with procurement calendar awards from national defense departments providing counter-cyclical revenue visibility for prime aerospace contractors. Yet, private sector capital expenditure across cross-border supply chains remains disciplined. Logistics data and freight metrics suggest that global manufacturing firms have not yet committed capital to inventory expansion, preferring lean intermediate holdings until the concrete parameters of future bilateral export controls, technology ring-fencing, and maritime security agreements are formally established.
Fixed income and currency desks mirrored this calculated restraint. The compression of sovereign yield volatility observed during Monday's trading did not translate into aggressive duration extension. Instead, liquidity remained concentrated at the front end of sovereign yield curves, where yields still offer compelling carry relative to the uncertain tail-risk profile of long-dated paper. Institutional treasuries are acutely aware that any diplomatic consensus reached in forthcoming executive bilateral meetings could easily be recalibrated by domestic political considerations or persistent structural disputes surrounding technology transfer and export regimes.
For Zurich-based wealth and institutional asset managers, the current market dynamic demands analytical rigor over momentum-chasing. The reflexive bid into equities ahead of major geopolitical summits historically yields compressed execution windows, where sentiment-driven gains are prone to swift reversals upon the publication of joint communiques lacking actionable policy mechanics. The unrelenting sovereign absorption of physical gold confirms that balance sheets of last resort continue to de-risk against structural fiat weaponization and systemic counterparty hazards.
Fairclough Palmer AG maintains that structural portfolio construction must remain insulated from headline-driven diplomatic cycles. While short-term volatility indicators may compress as political counterparts convene, the enduring trend toward regional economic blocs, strategic mineral localization, and balance-sheet autonomy remains the dominant macro determinant. Portfolios configured for long-term capital preservation must balance participation in near-term liquidity rallies with systematic allocations to unencumbered hard assets and capital-disciplined balance sheets capable of withstanding prolonged geoeconomic friction.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.