Energy Infrastructure Shocks
Pipeline Disruption Exposes Fragility in Hydrocarbon Logistics
15 September 2026
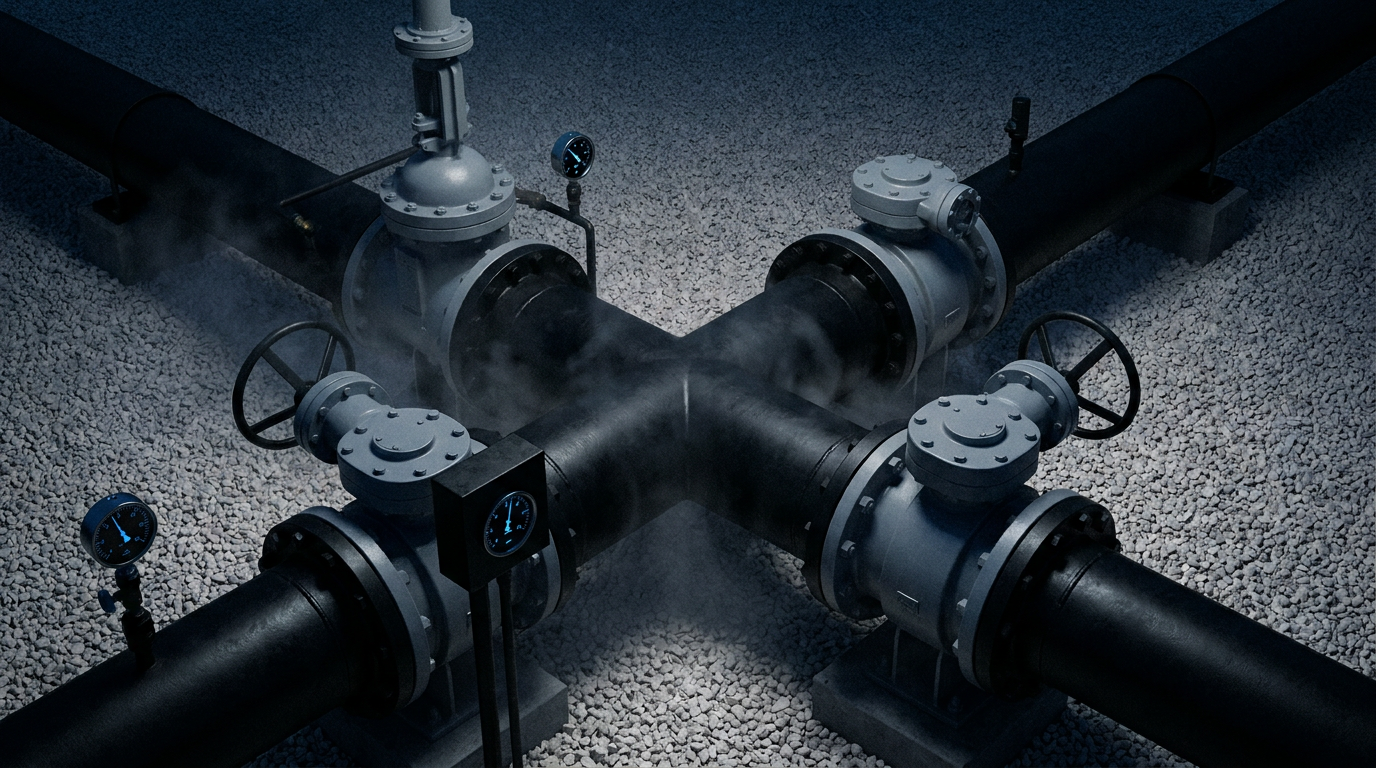
On Monday, global energy markets registered renewed friction following kinetic attacks that forced an abrupt operational halt along a primary Saudi crude pipeline corridor. The immediate consequence was swift across European and Asian trading desks: Continental natural gas futures jumped more than 6%, while benchmark crude benchmarks firmed despite an overarching macroeconomic environment characterized by tightening liquidity and elevated sovereign yields. For institutional allocators, the disruption served as an abrupt reminder that geopolitical vulnerability remains a stubborn tail risk within global supply chains, even as broader capital markets focus heavily on monetary policy timelines.
The physical crude market felt the impact almost instantaneously. Refiners across the Asia-Pacific region, heavily reliant on consistent crude flows from the Arabian Gulf, began seeking alternative sweet and medium-sour grades on short notice. Spot freight indications and insurance premia for Gulf transit immediately reflected the elevated operational risk. Simultaneously, European gas hubs experienced a reactive repricing; with storage injections progressing into the late-summer window, any potential displacement of liquid fuel supplies to power generation and industrial applications threatens to complicate the continent's baseline energy balance entering the fourth quarter.
Beyond wholesale energy benchmarks, the ripple effects are already migrating downstream into petroleum-derived consumables and industrial chemicals. The refined products market, which had maintained relatively thin operating buffers, faces localized inventory pinches in base oils and industrial lubricants. Visible reflections of this pressure appeared across retail and wholesale distribution networks on Monday, exemplified by volume rationing and upward price adjustments on finished motor oils across major consumer warehouse channels. Such frictions demonstrate that crude flow disruptions do not remain confined to upstream balances; they pass rapidly into maintenance logistics, freight fleets, and industrial equipment operations.
Intriguingly, the traditional playbook for geopolitical crises did not manifest across precious metals. Rather than catching a safety bid, gold and silver traded lower on Monday, with silver sliding below 64 dollars per ounce. The dynamic illustrates the prevailing tension between headline geopolitical disruption and the relentless upward pressure from global interest-rate expectations. Because the energy price surge reinforces inflationary stickiness, the primary market interpretation centered on prolonged central bank discipline rather than systemic capital preservation. Consequently, non-yielding monetary assets absorbed liquidations as dollar funding costs and real yields maintained upward momentum.
For corporate treasuries and portfolio managers operating out of Zurich and broader European hubs, this episode underscores the dual-headed nature of modern supply shocks. When physical infrastructure impairments coincide with already restrictive financial conditions, the transmission mechanism bypasses equity valuations and targets input costs directly. Energy-intensive manufacturing and logistics operations must now factor in heightened spot volatility alongside elevated borrowing costs. Fairclough Palmer AG notes that strategic positioning requires rigorous stress-testing against combined shocks: sustained energy supply bottlenecks accompanied by stubbornly elevated discount rates, rather than assuming one will counteract the other.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.